
A bank advertises a personal loan at “15 percent markup,” but your monthly instalment looks much higher than you expected. The reason is usually not a hidden trick. It is the way markup is calculated. If you learn to calculate markup on a personal loan, you can check an offer before you sign and compare two banks fairly. This guide explains the formula, shows a worked example, and warns about the “flat rate” trap.
What Is Markup on a Personal Loan?
In Pakistan, banks often call interest “markup.” It is the cost of borrowing money, shown as a yearly percentage. Islamic banks use the word “profit rate,” and the maths works the same way. Your bank adds the markup to the amount you borrow, and you repay both in monthly instalments, called EMIs.
How Banks Set the Markup Rate
Most bank loans in Pakistan are floating-rate loans. The rate has two parts:
- KIBOR: the Karachi Interbank Offered Rate, a benchmark that banks quote each working day.
- Spread: an extra percentage the bank adds for its own cost and risk.
Markup rate = KIBOR + spread
The State Bank of Pakistan (SBP) raised its policy rate by 0.50 point to 12 percent from 27 October 2026. On 12 November 2026, the 6-month KIBOR offer rate was 12.39 percent and the 1-year rate was 12.78 percent. Banks reset floating rates at fixed intervals, so your instalment can change when KIBOR changes.
The spread differs by bank and by borrower. It depends on your income, employer, and credit history. Ask your bank which KIBOR tenor it uses and how often it resets the rate.
The Formula to Calculate Your EMI
Most banks use the reducing balance method. You pay interest only on the amount you still owe, not on the original loan. The EMI formula is:
EMI = P × r × (1 + r)^n ÷ [(1 + r)^n − 1]
- P is the loan amount.
- r is the monthly rate, which is the yearly rate divided by 12.
- n is the number of monthly instalments.
You can type this into a spreadsheet, or use your phone’s calculator. Total markup is simply total repayment minus the loan amount.
Worked Example
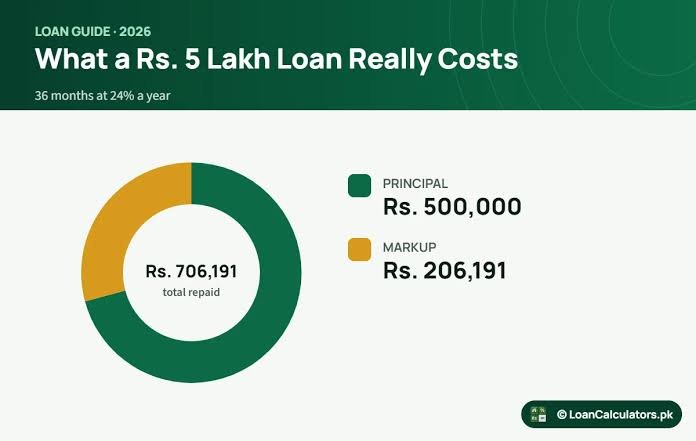
Take a Rs500,000 loan for 36 months. Assume 6-month KIBOR of 12.39 percent plus a spread of 3 percent. That gives a yearly markup of 15.39 percent. The spread of 3 percent is only an illustration, so use your own bank’s figure.
- Monthly rate: 15.39 ÷ 12 = 1.2825 percent.
- EMI: about Rs17,428.
- Total repayment: Rs17,428 × 36 = about Rs627,419.
- Total markup paid: about Rs127,419.
In the first month, the markup part of your instalment is Rs500,000 × 1.2825 percent = about Rs6,413. The remaining Rs11,016 reduces the loan. Over time, the markup share falls and the principal share rises.
How Tenor Changes the Cost
A shorter loan costs less in total markup, but the instalment is higher. The table compares the same Rs500,000 loan at 15.39 percent.
| Tenor | Monthly EMI | Total Repayment | Total Markup |
|---|---|---|---|
| 24 months | About Rs24,336 | About Rs584,066 | About Rs84,066 |
| 36 months | About Rs17,428 | About Rs627,419 | About Rs127,419 |
Choose the shortest tenor you can afford. Also check whether the bank charges a penalty for early repayment.
Watch Out for the Flat Rate
Some lenders quote a flat rate. A flat rate applies the markup to the full loan amount for the entire period, even as you repay it. This makes it far more expensive than a reducing balance rate at the same number.
| Method (15.39%, Rs500,000, 36 months) | Monthly EMI | Total Markup |
|---|---|---|
| Reducing balance | About Rs17,428 | About Rs127,419 |
| Flat rate | About Rs20,301 | About Rs230,850 |
A 15.39 percent flat rate works out to roughly 26.6 percent on a reducing balance basis. Therefore, always ask whether a quoted rate is flat or reducing, and compare offers on the same basis.
Fees That Add to the True Cost
Markup is not the only cost. Check your bank’s schedule of charges and your offer letter for:
- Processing fee.
- Insurance and documentation charges.
- Late payment charges.
- Early settlement or prepayment charges.
- Taxes on fees.
Add the fees to the total markup to see the real cost of the loan. If two banks quote the same markup, the one with lower fees is cheaper. For help with the fee list, see our guide on how to read a bank’s schedule of charges in Pakistan.
What SBP Says Banks Must Tell You
SBP guidelines, as described in recent guides, say a bank must disclose key terms with a loan offer, including the basis of the markup and the fees and charges. They also say the bank must give at least 30 days’ written notice before it varies the markup rate or how it is calculated. Read your offer letter closely, and keep a copy.
Tips Before You Take a Personal Loan
- Compare offers from at least three banks on the same tenor and amount.
- Ask for the KIBOR tenor, the spread, and the reset frequency in writing.
- Confirm that the rate is reducing balance, not flat.
- Make sure the EMI is no more than a comfortable share of your monthly income.
- Ask for the full repayment schedule before you sign.
- Avoid borrowing more than you need.
Frequently Asked Questions
How do I calculate markup on a personal loan?
Use the EMI formula with the monthly rate and the number of months. Total markup equals total repayment minus the loan amount.
What is KIBOR?
KIBOR is the Karachi Interbank Offered Rate, the benchmark banks use to price floating-rate loans.
What is the difference between flat and reducing balance?
A flat rate charges markup on the full loan for the whole period. A reducing balance rate charges markup only on the amount still owed, so it costs less.
Does my instalment change if KIBOR changes?
On a floating-rate loan, yes. The bank resets the rate at the agreed interval.
Is the processing fee part of the markup?
No. It is a separate charge, but you should add it to the total cost.
Conclusion
To calculate markup on a personal loan, add the spread to KIBOR, convert it to a monthly rate, and use the EMI formula. Check whether the rate is flat or reducing, and add every fee to get the true cost. The examples in this article are estimates, so confirm the exact figures in your bank’s offer letter. This article is for information only and is not financial advice. For more guides on money and daily services, keep following Pakistan Post. You can also check KIBOR rates on the State Bank of Pakistan website.
