
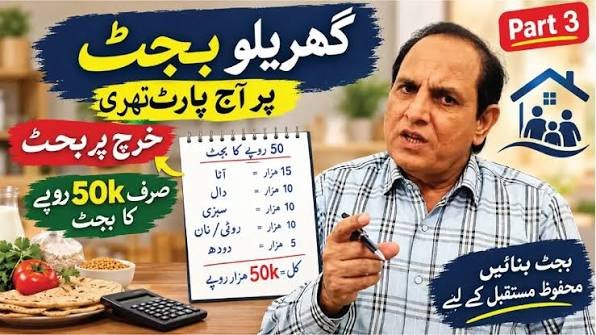
Prices rise, bills change every month, and salaries rarely stretch as far as we hope. A simple plan can help. This guide shows you how to build a monthly household budget in Pakistan in about an hour, using real numbers from your own life. You will get a step-by-step method, a sample budget, and tips to handle rising prices.
Why Budgeting Matters More in 2026
Pakistan’s inflation was 9.6 percent in October 2026, according to the Pakistan Bureau of Statistics (PBS). Food and non-alcoholic beverage prices rose 7.74 percent, and utility costs, including housing, water, electricity, and gas, rose 11.03 percent. At that pace, a basket that costs Rs80,000 today could cost about Rs87,700 in a year.
A budget does not make prices fall. It does show where your money goes, so you can cut waste, protect essentials, and save something each month.
Step 1: List Your Monthly Income
Write down every source of money that arrives in a normal month:
- Salaries of all earning family members.
- Business or shop income, using an average of the last three months.
- Rent from property.
- Remittances from family abroad.
- Any regular support or pension.
Use take-home income, after tax and deductions. If your income varies, use the lowest recent month as your base, and treat extra money as a bonus.
Step 2: Track Your Spending for One Month
Most people guess their spending wrongly. For one month, record everything. Use bank and wallet statements, Raast and mobile wallet history, receipts, and a small notebook for cash. Sort each expense into a category. This step gives your budget a realistic starting point.
Step 3: Group Expenses Into Categories
Split spending into fixed and variable costs. Fixed costs stay roughly the same each month. Variable costs change.
| Type | Examples |
|---|---|
| Fixed | Rent, school fees, loan EMIs, insurance, committee (kameti) payments |
| Variable essentials | Groceries, electricity, gas, petrol, mobile and internet, medicine |
| Flexible wants | Eating out, shopping, subscriptions, outings |
| Savings and goals | Emergency fund, Eid and wedding fund, education fund, gold or investments |
Step 4: Set Limits for Each Category
Use the tracking month as a guide, then set a limit for each category so that total spending is below your income. Aim to keep needs below about two-thirds of income, wants at 10 to 20 percent, and savings at 10 to 20 percent. These shares are a flexible guideline, not a rule. A low-income household may start with a smaller savings share and raise it over time.
Sample Monthly Budget for Rs80,000
This is an illustration only. Your numbers will differ by city, family size, and lifestyle.
| Category | Amount | Share of Income |
|---|---|---|
| Rent or housing | Rs20,000 | 25% |
| Utilities (electricity, gas, water, internet) | Rs10,000 | 12.5% |
| Food and groceries | Rs22,000 | 27.5% |
| Transport and fuel | Rs8,000 | 10% |
| Education | Rs6,000 | 7.5% |
| Healthcare | Rs3,000 | 3.75% |
| Savings and emergency fund | Rs6,000 | 7.5% |
| Miscellaneous and wants | Rs5,000 | 6.25% |
| Total | Rs80,000 | 100% |
Step 5: Pay Yourself First
Do not save what is left at the end of the month, because usually nothing is left. Instead, move your savings amount to a separate account or wallet on payday. Even Rs2,000 or Rs3,000 is a good start. Build an emergency fund that covers three to six months of essential costs, and keep it somewhere easy to access.
Step 6: Plan for Irregular Costs
Many budgets fail because of big annual expenses. Divide each one by 12 and set aside that amount every month. Common examples include:
- Eid and Ramadan spending.
- School admission and annual fees.
- Vehicle token tax, insurance, and repairs.
- Weddings and family events.
- Summer electricity bills, especially if you use an air conditioner.
For example, if you need Rs24,000 for Eid, save Rs2,000 a month. For summer bills, see our guide on how to estimate inverter AC electricity cost.
Step 7: Keep Debt Under Control
If you have loans or instalments, list them with the markup rate and the monthly EMI. A common rule of thumb is to keep total EMIs at around a third of your income or lower. Pay off high-cost debt first, such as credit card balances. Before you take a new loan, learn how to calculate markup on a personal loan so you know the true cost.
Step 8: Review Every Month
A budget is a living plan. At the end of each month:
- Compare your planned and actual spending.
- Find the categories you overspent.
- Adjust next month’s limits.
- Move any leftover money to savings.
Update the whole budget every few months, because prices and bills change. If prices keep rising near 10 percent a year, your food and utility limits may need to rise too, and you may need to trim wants.
Simple Ways to Cut Costs
- Buy staples in bulk from wholesale markets when you can store them.
- Compare prices at two or three shops before buying large items.
- Use LED bulbs and efficient fans, and use air conditioners at a higher temperature.
- Cut unused subscriptions and extra mobile packages.
- Plan weekly menus to reduce food waste.
- Combine trips to save fuel or fares.
Tools to Help You Budget
You do not need special software. A notebook, a phone spreadsheet, or a notes app is enough. If you prefer an app, see our list of productivity apps for students, many of which also work for tracking tasks and money. Check your mobile wallet and bank history for an automatic record of spending.
Common Budgeting Mistakes
- Skipping the tracking step and guessing.
- Making the budget too strict, so you give up after two weeks.
- Forgetting irregular costs.
- Not saving anything because “there is nothing left.”
- Never reviewing the plan.
Frequently Asked Questions
How do I make a household budget in Pakistan?
List your income, track spending for a month, group expenses, set limits, save first, and review monthly.
How much should I save each month?
Aim for 10 to 20 percent of income if you can. If that is hard, start small and increase it gradually.
How do I budget with rising prices?
Review your budget every month, protect food, utilities, and rent first, and trim wants. Inflation was 9.6 percent in October 2026.
What is an emergency fund?
It is money kept aside for unexpected costs, ideally three to six months of essential expenses.
Do I need an app to budget?
No. A notebook or spreadsheet works fine.
Conclusion
A monthly household budget in Pakistan starts with simple steps: know your income, track your spending, set limits, and save first. Review it every month, especially when prices are rising. The sample budget is only an illustration, so adjust every amount to your own family. This article is for information only and is not financial advice. For more practical guides, keep following Pakistan Post. You can also check inflation data on the Pakistan Bureau of Statistics website.
